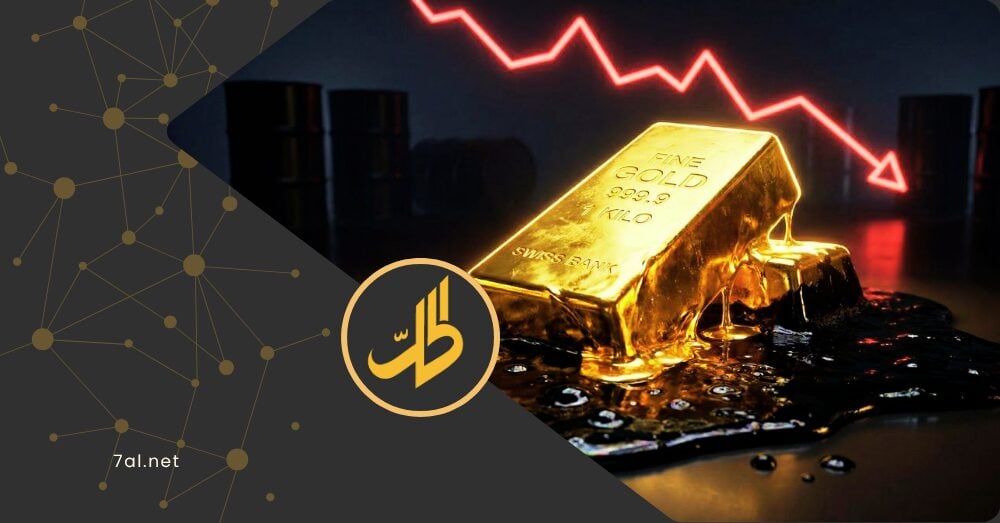
In a striking paradox that upended conventional market dynamics, the war in Iran has failed to boost demand for gold as the leading safe-haven asset. Instead, in an unprecedented development, it has curbed global appetite for the yellow metal, in one of the most counterintuitive outcomes of geopolitical conflict in recent decades.
Since military operations escalated and the Strait of Hormuz was closed to a large share of oil tankers, the markets have not seen the steady rise in gold prices that had been expected. Instead, the price per ounce has posted a sharp and sustained decline.
A sharp drop shatters expectations
According to data issued by Bloomberg and the World Gold Council on March 25, the spot gold price fell from its highest level this year of $5,595 per ounce to $4,420 in trading on March 28, a decline of 21 percent in just five weeks and the biggest quarterly drop since 2021.

This decline was not merely a technical correction, but a reflection of a fundamental shift in the behavior of both institutional investors and central banks, which were forced to liquidate part of their gold holdings to secure urgent liquidity as a result of the war’s repercussions.
The Iran war indirectly curbed global buying appetite: the more gold rose, the more consumer demand retreated, and the more cautious major investors became, especially when prices themselves turned into a barrier to further entry into the market. Purchases of gold jewelry fell by 18 percent under pressure from high prices, while in China they plunged 24 percent to their lowest level since 2009.
Central banks between buying and liquidation
Data in recent years showed that about 95 percent of central banks were moving toward increasing their gold reserves as part of a long-term strategy to strengthen financial stability.
The war in Iran created partial exceptions to this trend, especially for countries facing acute monetary pressures or shortages of foreign exchange, which may push them to liquidate a limited portion of their reserves to cover urgent needs, such as financing energy imports or propping up local currencies.
In this context, economic researcher Yahya al-Sayyid Omar explained in a Facebook post that the repercussions of the war in Iran have markedly reshaped the priorities of global markets, stressing that these geopolitical developments have pushed investors and monetary policymakers to reassess traditional hedging tools, foremost among them gold, which has regained its position as one of the leading safe havens in times of turmoil and uncertainty.
Gold: the last line of defense
Omar explained that central banks, despite resorting in some exceptional cases to selling a limited portion of their reserves to secure urgent liquidity, handle this step with extreme caution, given that gold represents a fundamental pillar for preserving value over the long term, in addition to its pivotal role in hedging against inflation and mounting economic risks.

He added that gold is the last line of defense for monetary policy, as it retains its ability to hold firm even amid declining confidence in markets or currency turmoil, giving it the status of a sovereign asset that is difficult to part with. He noted that escalating geopolitical tensions usually drive central banks to hold on to their gold reserves or increase them, rather than sell them, because any major reduction in those reserves could be interpreted as a sign of weakness, negatively affecting market confidence and intensifying financial volatility.
He indicated that the prevailing trend in recent years had clearly leaned toward increasing gold holdings, as estimates showed that about 95 percent of central banks expected to raise their reserves within a long-term strategy to enhance financial stability.
Calculated selling under crisis pressure
However, the war in Iran imposed a more complex reality, pushing some countries, especially those facing acute monetary pressures or shortages of foreign exchange, to liquidate a limited portion of their reserves to cover urgent needs, such as financing energy imports or propping up local currencies.
Such sales are not carried out randomly, but are subject to precise calculations and executed gradually in stages, with the aim of avoiding market shocks or causing a sharp drop in prices, citing the example of Turkey, which sold about 60 tons of gold to support its currency and boost liquidity.
Economic researcher Yahya al-Sayyid Omar
He pointed out that these operations may lead to an increase in supply in global markets, which is sometimes reflected in temporary price declines, concluding by stressing that selling gold under such circumstances does not reflect a strategic shift so much as it represents a short-term tactical measure for crisis management. He stressed that the yellow metal will remain a sovereign financial instrument that retains its importance in protecting economies from major shocks, with central banks expected to return to increasing their reserves once pressures recede and a degree of stability is restored in global markets.
Fund outflows and a shift in liquidity
Alongside central bank moves, data from gold exchange-traded funds (ETFs) confirm this unprecedented trend. According to a Reuters report, global funds recorded outflows of about 48 tons in the past two weeks alone, the highest level of selling since the start of the war in Ukraine.

The biggest sell-offs were in North American and European funds, where investors preferred to hold cash or turn to short-term US Treasury bonds, which have begun yielding positive real returns for the first time in years. This shift in demand, along with the announcement of the discovery of a new gold mine in China with estimated reserves of about 328 tons, according to Xinhua this March, increased structural pressure on prices.
In sum, it can be said that the Iran war has not only killed appetite for buying gold, but has also exposed the fragility of the assumption that safe havens always remain in demand in times of danger. War itself, with its rising oil and financial costs, may become the reason for draining the liquidity available for buying, turning gold itself from a haven into a source of emergency financing.
- How the Houthis Are Choking Yemen’s Peace Efforts with a Broad Escalation on the Ground
- Economy in the Wind: How Yemenis Are Paying the Price of Disrupted Shipping Routes
- Houthi Summer Centers: Factories for Indoctrination and Raising a “Scream” Generation
- The “Coalition of Necessity”: What Costa Rica’s Terrorism Designation of the Houthis Signifies
- Mojtaba Khamenei Runs Iran from His Bed as Photos Vanish and the Supreme Leader Makes a “Voice-Only” Appearance